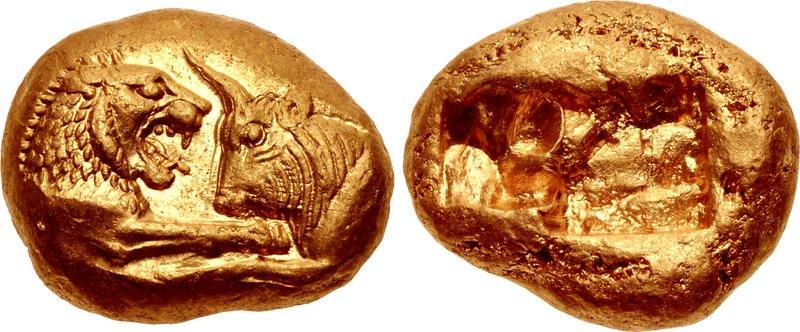
The gold standard and Bretton Woods, explained
For about a century, many currencies were defined as a fixed weight of gold. Here is how the gold standard worked, how Bretton Woods replaced it and why it ended in 1971, told as monetary history.
This page explains monetary history neutrally. It does not argue for or against any monetary system and is not financial advice.
What a gold standard is
Under a gold standard, a country defines its currency as a fixed weight of gold and promises to exchange paper money for gold at that rate. If one dollar equals a set fraction of an ounce, then the price of gold in dollars is fixed by law. Banknotes become claims on gold held by the government or central bank.
There were several versions:
| System | How it worked |
|---|---|
| Gold specie standard | Gold coins circulate as everyday money |
| Gold bullion standard | Coins do not circulate, but large amounts of paper money can be swapped for gold bars |
| Gold exchange standard | A country holds reserves in another currency that is itself convertible into gold |
Britain leads the way
Britain moved toward gold in the 18th century. In 1717, Isaac Newton, then Master of the Royal Mint, set the value of the gold guinea in silver shillings at a rate that ended up favoring gold. Britain formally adopted a gold standard in the early 19th century, with the gold sovereign coin introduced in 1817.
The classical gold standard
From the 1870s, many major economies, including Germany, France and the United States, moved onto gold. The period up to 1914 is called the classical gold standard. The US formally adopted it in law with the Gold Standard Act of 1900, at a price of $20.67 per troy ounce.
Because each currency was fixed to gold, exchange rates between them were effectively fixed too, which made international trade and lending more predictable. The trade-off was that a country's money supply was tied to its gold reserves, so governments had little room to respond to downturns, and new gold discoveries could affect prices worldwide.
Suspension and the interwar years
Most countries suspended gold convertibility in 1914. Attempts to restore the system in the 1920s led to a weaker gold exchange standard. During the Great Depression of the early 1930s, countries left gold one by one: Britain in 1931, and the United States changed its system in 1933 and 1934, restricting private ownership of gold bullion and revaluing gold from $20.67 to $35 per ounce. Many economic historians link the timing of leaving gold to the timing of recovery from the Depression, though the subject is still studied.
Bretton Woods
In July 1944, delegates from 44 countries met at Bretton Woods, New Hampshire, to design a new international monetary system. The agreement created the International Monetary Fund and the World Bank, and it set up a system of fixed but adjustable exchange rates:
- The US dollar was fixed to gold at $35 per troy ounce.
- Other currencies were fixed to the dollar.
- Foreign central banks could exchange their dollars for US gold at $35.
Ordinary people could not redeem dollars for gold. Only official institutions could.
Strains and the end
By the 1960s, more dollars were held abroad than the US gold stock could cover at $35. A group of central banks called the London Gold Pool sold gold to hold the market price near $35, but the pool collapsed in 1968, and a two-tier market emerged, with an official price and a separate free market price.
On August 15, 1971, the United States suspended the convertibility of dollars into gold for foreign central banks. After a short attempt to set new fixed rates, major currencies moved to floating exchange rates by 1973. The official link between money and gold was over. In the US, private ownership of gold bullion became legal again at the end of 1974.
Gold after the gold standard
Since 1971, the gold price has been set by the market. It rose to about $850 per ounce in January 1980, fell back for two decades, climbed to around $1,900 in 2011, passed $2,000 in 2020 and broke $4,000 for the first time in October 2025. Central banks still hold large gold reserves, and many have been net buyers in recent years. For what drives the price today, read what moves the gold price.
Past prices are history, not a forecast. Nothing here is financial or investment advice.